Wall Street is climbing without the consumer.
Over three months, the S&P 500 has gained 4.3%, while the consumer staples ETF (XLP) has lost about 4%, and its discretionary counterpart (XLY) about 5%.
Bespoke Investment’s senior expert Paul Hickey blames higher Treasury yields and fuel costs: the 10-year yield is hovering around record levels (above 5.3%) – and diesel is up some 68% since the Iran war started.
Meanwhile, wage growth of about 3% trails 3.4% inflation.
According to Telsey Advisory’s lead consumer analyst Joe Feldman though, a few consumer names have now bottomed and are worth buying heading into 2027.
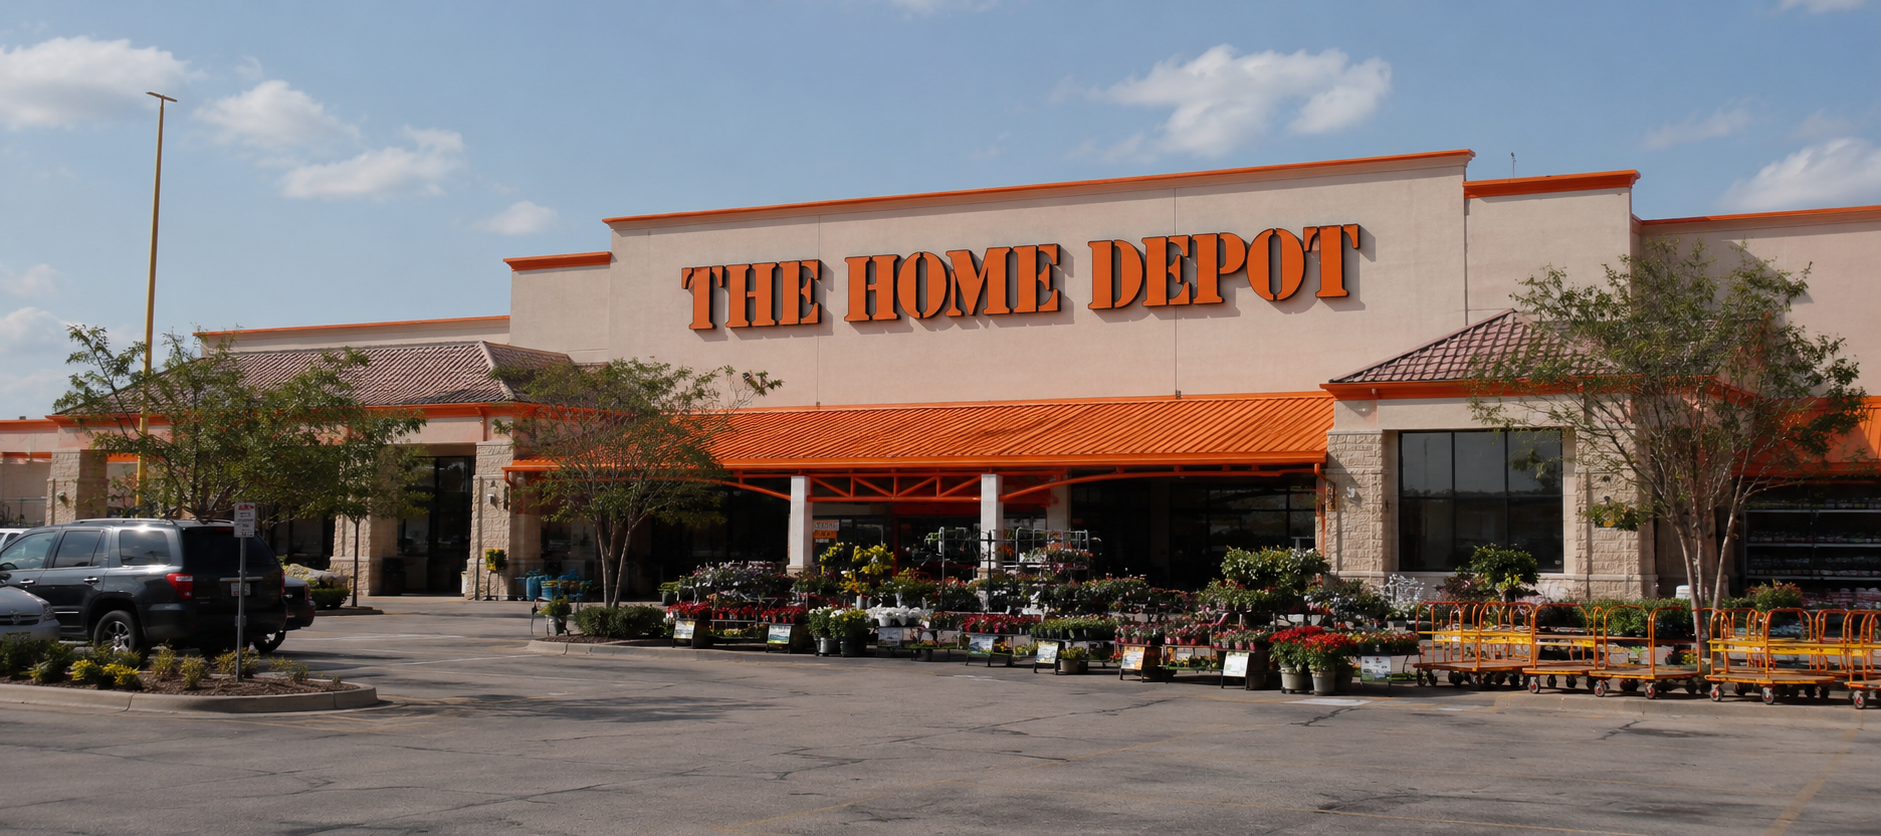
Home Depot (HD)
Home Depot stock has been under immense pressure, losing some 18% in three months – a reaction to a housing market squeezed by tight supply and higher mortgage rates, which take their cue from the 10-year Treasury yield.
Affordability has suffered.
The company’s operating record has not. It has posted seven straight quarters of comparable-store sales growth, and Telsey analyst Feldman expects the run to continue through the back half of the year.
In his telling, HD is taking market share even with the macro backdrop under significant pressure.
As of writing, the home improvement retailer is trading at less than 2x sales, which signals a huge discount to its historical averages.
McDonald’s (MCD)
“Pretty solid numbers” is how Feldman described McDonald’s latest financials – a verdict at odds with an 18% share-price slide over three months.
Management has spent this year trying to win back lower-income customers while contending with a weaker perception of value.
Feldman says the chain keeps delivering even as consumer spending softens adding that temporary value-perception headwinds create an attractive entry point for a premier global franchisor.
McDonald’s unmatched scale, high-margin asset-light model, and robust balance sheet allow it to out-invest competitors in digital ordering and targeted promotions.
As value initiatives take hold, resilient earnings and market-share gains should catalyze a valuation rebound. At about 6x sales, MCD shares are now available to load up on a discount, he noted.
TJX Companies (TJX)
TJX stock’s 10% decline is the shallowest of the three, and the one closest to a self-inflicted wound.
In the latest reported quarter, the owner of Marshalls and HomeSense carried the wrong mix of inventory that hurt parts of the business, though management says trends have since improved.
But the calendar offers some cover: the off-price retailer tends to thrive at the end of the year, when consumers hunt for well-priced finds.
TJX shares are currently trading at about 2.5x sales, a valuation multiple that offers a meaningful discount to long-term investors.
The retailer also pays a dividend yield of 1.38% as of writing, which makes it even more attractive for income-focused investors.
The post Three beaten down consumer stocks that are now screaming opportunity appeared first on Invezz
