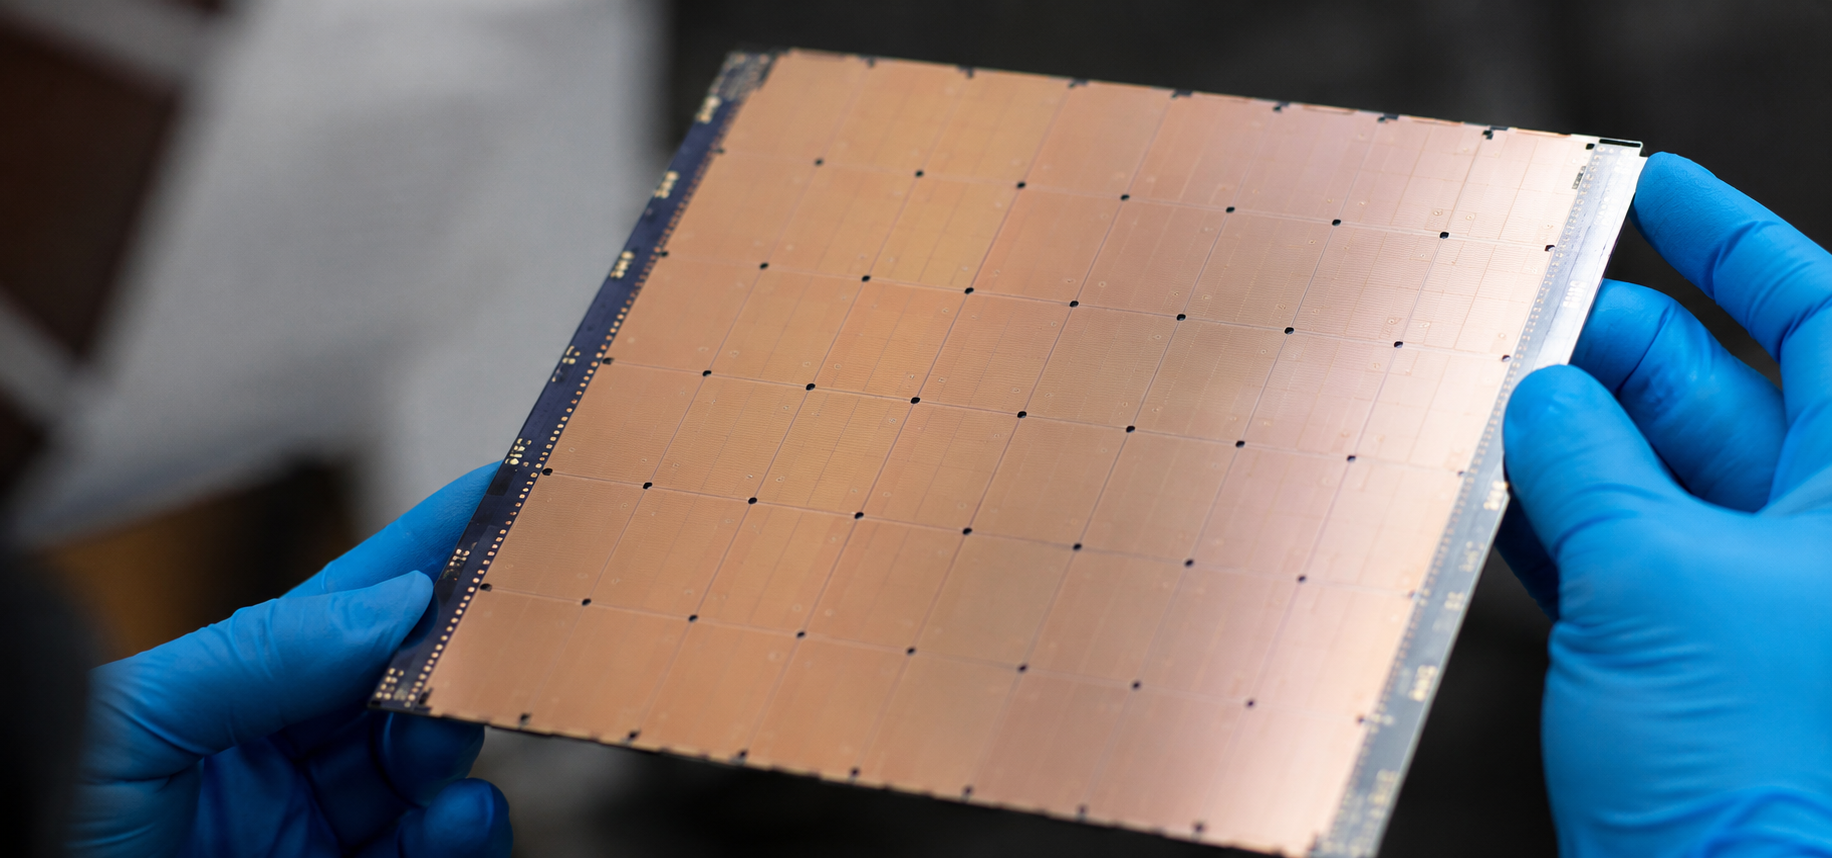
Cerebras Systems (CBRS) shares are extending losses on October 12th as investors continue to reassess the artificial intelligence (AI) infrastructure company’s future prospects.
CBRS is now trading at about half its price at the start of 2026, yet an illustrative discounted cash flow (DCF) analysis suggests it’s still overvalued for risk-averse investors.
For those interested in buying the dip in Cerebras stock, the central question is whether rapid sales expansion can ultimately translate into durable cash generation.
Our assumptions for the DCF model
Cerebras Systems’ latest outlook targets $880 million – $890 million in 2026 core revenue, while management plans to more than triple revenue in 2027.
Its $25.4 billion in remaining performance obligations (RPOs) provides substantial visibility into contracted business, although those commitments are not equivalent to immediate cash flow.
DCF’s base case assumes “economic revenue” reaches $2.8 billion next year, $10.5 billion in 2031, and $19.2 billion by 2036.
It also assumes free cash flow (FCF) margin improves from negative 25% to positive 22% over that period.
While these assumptions aren’t official company forecasts, they’re still ambitious given Cerebras must absorb considerable investment needed to expand computing capacity before delivering cash to shareholders.
Why CBRS shares are not undervalued yet
Discounting projected cash flows at 12% – with perpetual growth of 3% after 2036 – produces an estimated enterprise value of $21.2 billion.
Adding $6.2 billion in assumed adjusted net cash brings equity value to roughly $27.4 billion, and dividing that figure by an assumed 285 million diluted shares yields $96 fair value for CBRS stock.
The cash adjustment allows for spending after June, while the share count incorporates an allowance for warrants and employee equity. Neither represents a reported October balance-sheet figure.
Alternative scenarios demonstrate the uncertainty: weaker growth and profitability produce a value near $34 – while exceptional growth and a 30% terminal FCF margin support about $258 per share.
Cerebras Systems still requires exceptional execution
The DCF model suggests Cerebras shares look expensive under base assumptions, despite the selloff.
Holding margins, dilution, and discount rates constant, justifying $150.85 would require a revenue trajectory about 74% above the base case – reaching roughly$33 billion in 2036, alongside $7.3 billion in annual free cash flow.
Stronger margins or lower investment requirements could also support today’s valuation. However, about 72% of base-case enterprise value comes from the terminal value – making the result highly sensitive to distant expectations.
Investors should therefore treat $96 as a scenario estimate, rather than a precise price target.
In short, Cerebras Systems’ opportunity remains rather huge – but the company’s current price still demands considerable long-term success.
That said, Wall Street rates it at Buy currently, with a bullish mean price target of about $291.
The post DCF model suggests Cerebras stock is still overvalued appeared first on Invezz
